

Centre Reduces Custom Duty on Soya Palm Oil, Impact on Food Inflation and Domestic Refining
| General Studies Paper II: Government Policies and Interventions, Buffer Stocks & Food Security |
Why in News?
Recently, the Union Government reduced basic customs duty on crude soybean and palm oils from 10% to 5% effective September 24, 2026.
Highlights of Custom Duty Reduction on Soya Palm Oil
- Announcement: The Ministry of Finance, Department of Revenue notified the reduction of customs duty on crude soybean and palm oils on 23 September 2026 through Notification No. 31/2026-Customs (G.S.R. 840(E)).
- It amends Notification No. 45/2025-Customs, which governs the applicable concessional customs-duty structure.
- The notification derives authority from Section 25(1) of the Customs Act, 1962 and Section 3(12) of the Customs Tariff Act, 1975.
- Effective Date: The revised duty structure became effective from 24 September 2026, one day after notification.
- Customs Duty Changes:
- Crude soybean oil and crude palm oil now attract 5% Basic Customs Duty (BCD), compared with 10% earlier. Thus, the basic customs-duty component has been reduced by 5 percentage points, or effectively halved.
- For refined soybean oil and refined palm oil, BCD has been reduced from 32.5% to 27.5%.
- The government has made the largest change for crude sunflower oil, reducing BCD from 10% to Nil.
- BCD on refined sunflower oil has simultaneously fallen from 32.5% to 22.5%.
- After applicable Agriculture Infrastructure and Development Cess (AIDC) and Social Welfare Surcharge (SWS), crude palm and soybean oil are reported at approximately 11% total duty, down from 16.5%.
- BCD on refined sunflower oil has simultaneously fallen from 32.5% to 22.5%.
Rationale Behind the Reduction
- India is structurally dependent on imported edible oils because domestic production does not meet consumption requirements.
- Recent estimates put import dependence at roughly two-thirds of vegetable-oil demand, making international prices highly relevant to Indian food inflation.
- India currently imports about 55% to 60% of its total edible oil demand.
- Palm oil (crude and refined) makes up about 62% of India’s total edible oil imports.
- This is part of a continuing tariff-management approach. In May 2025, the government had reduced BCD on crude edible oils from 20% to 10%, lowering their effective duty to about 16.5% including AIDC.
- Edible oils are a mass-consumption commodity in India. Government data show per-capita edible-oil consumption reached 21.8 kg in 2023-24, compared with 19.8 kg in 2019-20, reflecting sustained domestic demand.
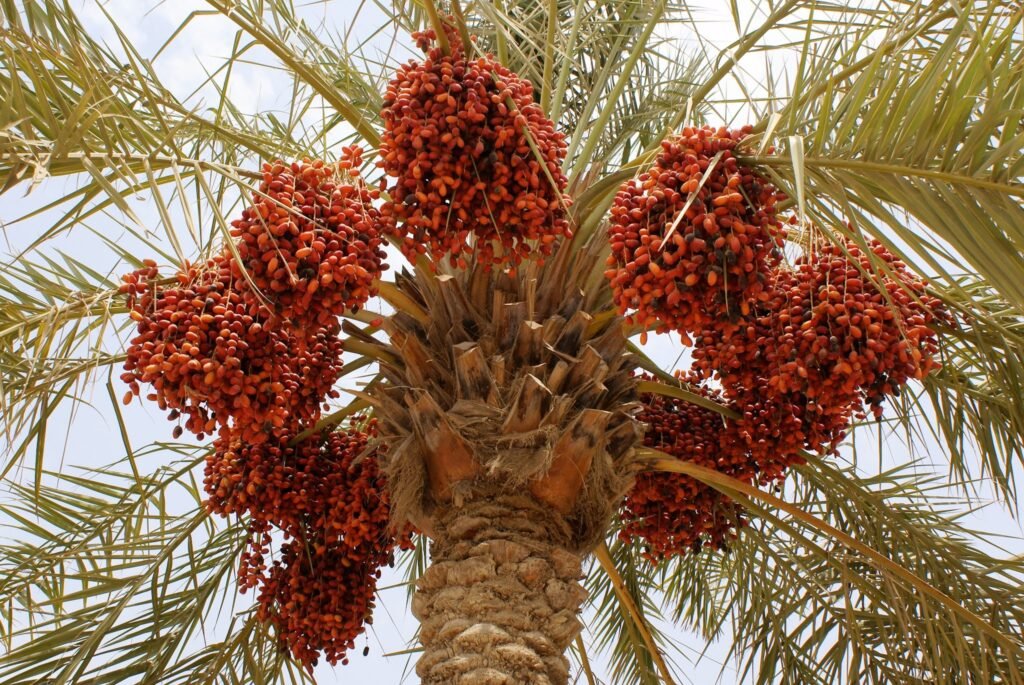
- Palm oil remains India’s largest imported edible oil because of its competitive pricing, high yield and extensive availability.
- During November 2025–June 2026, crude palm oil imports were approximately 49.4 lakh tonnes, major component of import basket.
- Soybean oil is India’s principal major soft-oil import. During November 2025–June 2026, India imported about 29.76 lakh tonnes of crude soybean oil and 2.98 lakh tonnes of refined soybean oil.
- Palm oil supplies are heavily connected with Indonesia and Malaysia, while soybean oil is sourced principally from Argentina and Brazil, with additional suppliers emerging. This makes India vulnerable to external supply, freight and geopolitical disruptions.
- Global biofuel mandates increasingly compete with food uses for vegetable oils. Biofuel expansion in Malaysia and the United States, can tighten global edible-oil supplies and raise international prices.
- Because imports are largely dollar-denominated, rupee depreciation raises landed costs even when international commodity prices remain stable.
- Recent industry data also identified currency weakness as an important factor behind higher Indian edible-oil costs.
- India’s domestic edible-oil production was estimated at around 9.6 million tonnes in 2025-26, covering roughly 40% of domestic requirements, while imports were projected at approximately 16.7 million tonnes.
- The September reduction is particularly significant because festive demand traditionally increases consumption of sweets, snacks and fried foods.
- Vegetable-oil prices had increased substantially over the preceding year, creating pressure ahead of the September–November festive season.
Status, Regulation and Government Initiatives
- Status: India is one of the largest producers of oilseeds globally, accounting for roughly 6% of worldwide oilseed production and covering about 20.8% of the global cultivation area.
- The primary cultivated oilseeds include soybean, groundnut, rapeseed-mustard, sunflower, sesame, safflower, niger, castor, and linseed.
- According to reports like NITI Aayog‘s, India ranks first globally in the production of specific items including castor seed, sesame, safflower, niger, and rice bran oil.
- Oilseeds represent the second-highest agricultural acreage and production value in India after food grains.
- Production is heavily concentrated in states like Rajasthan (leading in mustard), Madhya Pradesh (leading in soybean), Gujarat (leading in groundnut), and Maharashtra, which collectively drive the majority of the national output.
- Regulation: India presently allows edible-oil imports under the Open General Licence (OGL) framework.
- Edible oils (except coconut oil) are permitted for unrestricted import by private industry participants under OGL.
- The government periodically adjusts tariff rates to balance the interests of consumers, processors and farmers.
- Initiative:
- The National Mission on Edible Oils–Oilseeds (NMEO-Oilseeds), approved in October 2024 for 2024-25 to 2030-31, has an outlay of ₹10,103 crore.
- It aims to raise primary oilseed production from 39 million tonnes to 69.7 million tonnes by 2030-31.
- Together with NMEO-Oil Palm, the government targets domestic edible-oil production of 25.45 million tonnes by 2030-31, estimated to meet around 72% of projected domestic requirements.
- NMEO-Oilseeds uses more than 600 Value Chain Clusters across the country, linking farmers with FPOs, cooperatives, processors, seeds and market infrastructure. These clusters cover more than 10 lakh hectares annually.
- The programme promotes high-yielding and high-oil-content varieties, breeder-seed production, certified-seed distribution, demonstrations and improved agricultural practices.
- The NMEO-Oil Palm, launched in 2021-22, carries an outlay of ₹11,040 crore, including a ₹8,844-crore Central share. Its objective is to expand cultivation and increase domestic crude-palm-oil production.
- During 2021-22 to 2025-26, approximately 2.73 lakh hectares were brought under oil-palm cultivation.
- The government released ₹1,447.21 crore to implementing States during this period.
- Government policy combines MSP, procurement mechanisms and PM-AASHA interventions for oilseeds.
- The e-Vegetable Oils Platform (evegoils.nic.in) is an online portal launched by the Directorate of Sugar & Vegetable Oils.
- It was launched to collect monthly production data and manage registrations for edible oil units.
- The National Mission on Edible Oils–Oilseeds (NMEO-Oilseeds), approved in October 2024 for 2024-25 to 2030-31, has an outlay of ₹10,103 crore.
Impact of This Reduction
- Lower BCD reduces the tax component of the landed import cost. If international prices and exchange rates remain favourable, refiners can procure crude oil more cheaply, potentially transmitting savings to wholesalers and retail consumers.
- Edible oils are important food commodities, so lower import costs can moderate food-price pressures.
- Lower duties on crude oils relative to refined products preserve a duty differential, making domestic refining comparatively more attractive than importing finished refined oil.
- Cheaper imports can increase competitive pressure on domestically produced soybean and other oilseeds, particularly if imported oil becomes substantially cheaper than domestic alternatives.
- Lower duties can increase import demand, potentially increasing the edible-oil import bill if volumes rise faster than international prices fall.
- India is one of the world’s largest edible-oil importers. Increased Indian buying can tighten international availability and potentially influence global palm and soybean-oil prices.
- The policy has implications for major suppliers such as Indonesia, Malaysia, Argentina, Brazil, Russia and Ukraine.
- The reduction may reinforce India’s preference for crude imports followed by domestic refining.
- In November 2025–June 2026, crude oils accounted for about 85% of edible-oil imports, illustrating the importance of the crude-versus-refined duty differential.
Frequently Asked Questions (FAQs):
1. What is the new customs duty on soya oil?
Crude soybean oil’s Basic Customs Duty (BCD) has been reduced from 10% to 5%.
2. Has India reduced palm oil import duty?
Yes. BCD on crude palm oil has been reduced from 10% to 5%.
3. What is the latest edible oil import duty in India?
For crude soybean and palm oils, BCD is 5%; applicable cess and surcharge remain additional.
4. Why did the government change customs duty on edible oils?
The reduction aims to lower import costs, ease edible-oil inflation, and improve domestic availability ahead of festive demand.
5. What is the new tariff value of crude palm oil?
The latest tariff value is US$1,219 per metric tonne, effective from 16 September 2026.
6. What is the import duty on crude soybean oil?
Crude soybean oil now attracts 5% BCD; its latest tariff value is US$1,268 per metric tonne.
Disclaimer: Information in this article is based on official announcements and public records. Details may evolve over time.