

Government Revised Special Additional Excise Duty on Fuel Exports
| General Studies Paper II: Government Policies |
Why in News?
Recently, the Government revised Special Additional Excise Duty on fuel exports, effective October 16, 2026, adjusting petrol and diesel levies to balance availability.
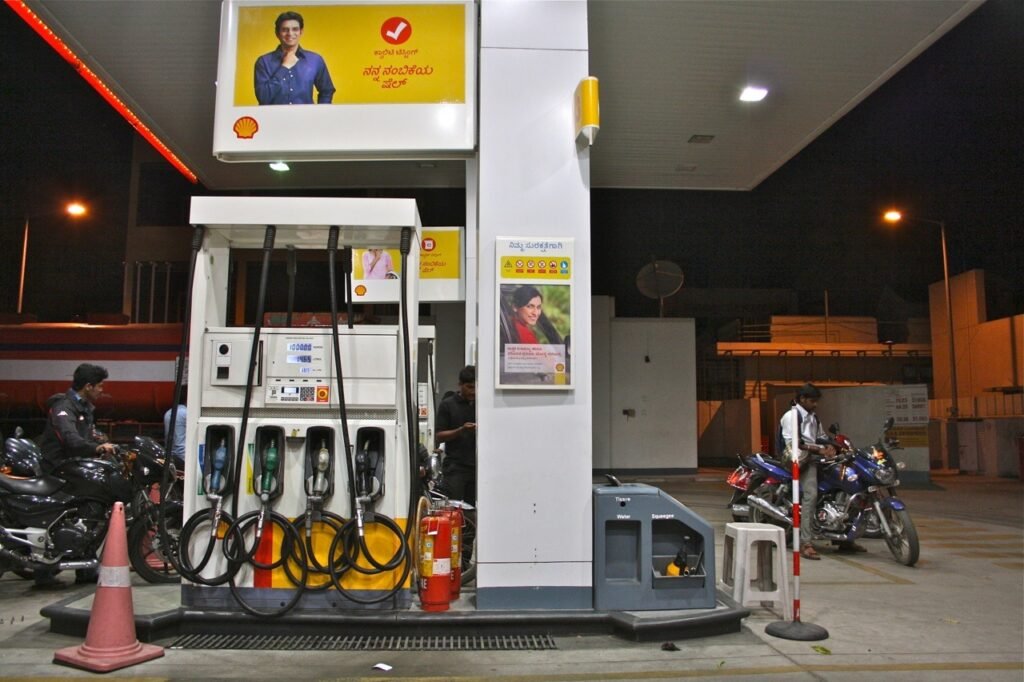
Highlights of India Petrol Export Tax Diesel Duty 2026 Revision
- Decision: The Government has implemented a critical fortnightly revision to its windfall tax (Special Additional Excise Duty) on fuel exports, effective October 16, 2026, to counter extreme volatility in global energy markets.
- The Finance Ministry has increased the windfall tax on petrol exports to ₹2.5 per litre from ₹0.5 per litre, while reducing the levy on diesel exports to ₹8.5 per litre from ₹16 per litre.
- The export duty on Aviation Turbine Fuel (ATF) has been retained at ₹10.5 per litre.
- The government clarified that there is no change in existing excise duty rates for petrol and diesel cleared for the domestic consumer market.
- Rationale: The government aims to safeguard domestic fuel availability by directly disincentivising oil refiners from prioritizing lucrative overseas markets.
- The government updates fuel export duties every two weeks to match global oil and petroleum price shifts.
- The policy ensures that adequate petroleum product supplies remain within the country during severe West Asia crises.
- Brent crude trades at approximately $105.16 to $105.34 per barrel, remaining firmly above the $100 threshold.
- Ongoing geopolitical conflicts involving the U.S. and Iran, security disruptions around the Strait of Hormuz, and constrained Middle East exports continue to command a “war risk premium“.
- Impact: Private and public oil refiners face altered gross refining margins (GRMs) as the tax directly captures their extraordinary, supernormal profits from international trade.
- Exemptions remain intact, meaning public sector oil companies exporting to neighboring nations like Nepal, Bhutan, and Bangladesh are protected from these duties.
- The strategic adjustment of duties serves as a flexible fiscal tool to balance international trade opportunities with national demands.
- This targeted windfall tax mechanism allows the state to boost government non-tax and excise revenues by capturing windfall gains generated during global geopolitical friction.
- By keeping domestic fuel taxes unchanged and securing local supply, the government successfully neutralizes direct cost-push inflation at the retail level.
- This prevents high international oil prices from directly bleeding into transportation, manufacturing, and mechanized farming costs.
- It assists the central bank in managing headline consumer price index (CPI) inflation, preventing global commodity volatility from heavily impacting household budgets.
- The entire fortnightly review framework acts as a structural shield for India’s long-term energy security amid compounding geopolitical disruptions.
What is Special Additional Excise Duty (SAED)?
- About: The Special Additional Excise Duty (SAED) is a specific type of indirect tax levied by the Central Government.
- It is an exceptional levy imposed over and above the Basic Excise Duty (BED).
- Often acting as a windfall tax, SAED is utilized to tax the supernormal profits earned by industries due to exceptional global market fluctuations.
- Basis: The structural basis of SAED relies heavily on external market conditions, such as global supply chain disruptions, geopolitical conflicts, and rising Gross Refining Margins (GRMs).
- Objective: It is primarily introduced to ensure domestic availability of critical commodities.
- It aims to disincentivize private players from prioritizing lucrative overseas exports over domestic needs.
- Authority: The legislative authority for SAED flows directly from Section 147 of the Finance Act, 2002, with the initial tariff frameworks detailed in its Eighth Schedule.
- The administration and operational oversight of this duty are managed by the Central Board of Indirect Taxes and Customs (CBIC) under the Ministry of Finance.
- Mechanism: The SAED operates through a flexible, ad-hoc regulatory mechanism where rates are adjusted via official gazette notifications.
- The Ministry of Finance conducts a fortnightly review to recalibrate the duty based on a moving average of international crude oil and fuel product prices.
- The collected proceeds remain with the Centre as it is generally levied as a specialized surcharge.
- Products Covered: The coverage of SAED is narrowly targeted at high-revenue un-subsumed petroleum products that sit outside the core Goods and Services Tax (GST) framework.
- The primary products subjected to this volatile duty include petrol, high-speed diesel, and Aviation Turbine Fuel (ATF).
- The government implemented export duties on diesel and aviation turbine fuel (ATF) on March 27, 2026, followed by a corresponding levy on petrol exports starting May 16, 2026.
- These dynamic export-focused SAED rates explicitly do not alter the excise duty structure meant for domestic consumption.
Frequently Asked Questions (FAQs):
1. Why has India increased the petrol export tax in 2026?
To discourage excessive exports, protect domestic fuel availability and adjust taxation amid volatile international petroleum prices.
2. What is the new petrol export tax rate?
The petrol export duty increased from ₹0.50 to ₹2.50 per litre, effective 16 October 2026.
3. Why has the government reduced diesel export duty to ₹8.5 per litre?
The government adjusts duties to reflect international price movements; the notification does not specify a separate reason for the diesel-duty reduction.
4. When will the revised petrol and diesel export duties take effect?
Both revised rates took effect on 16 October 2026, applying to the following fortnight.
5. How will the export tax changes affect Indian oil refineries?
Higher petrol duties may reduce export margins, while lower diesel duties may improve diesel-export competitiveness; actual effects depend on prices and export volumes.
Disclaimer: Information in this article is based on official announcements and public records. Details may evolve over time.